A Straw Hat at Account Number 0001: How Community Banking and Respect Shaped Our Town
Introduction: A Routine Visit Becomes Transformational
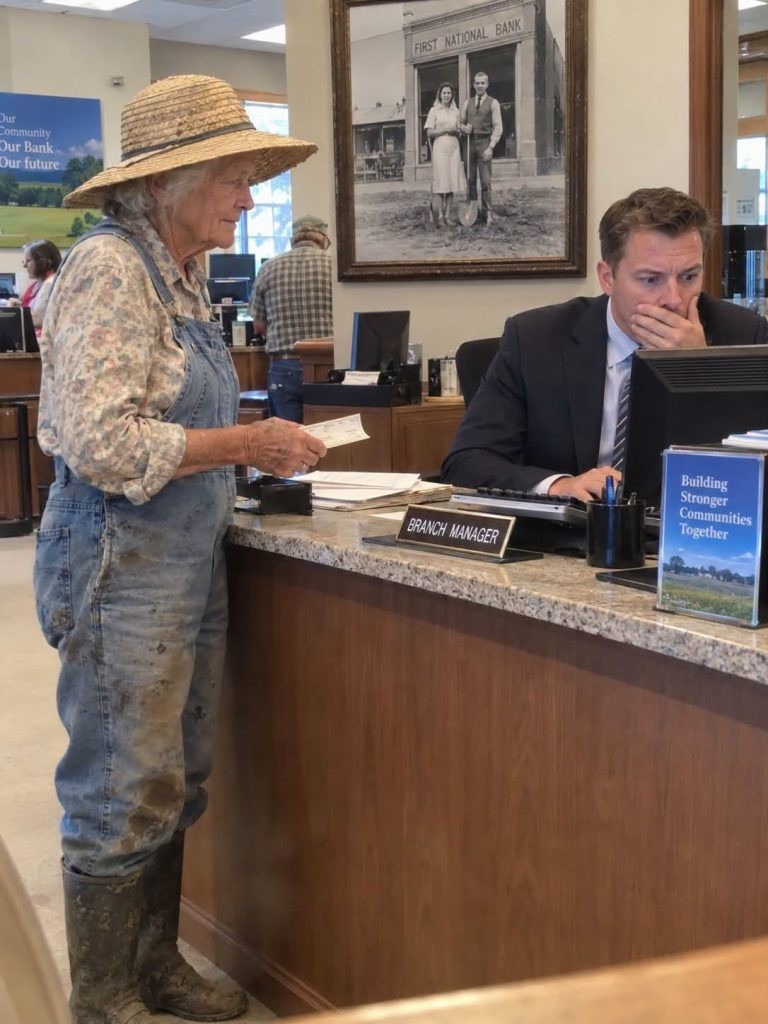
On an ordinary morning, dressed in gardening clothes, a straw hat, and muddy green boots, a widow set out with a simple goal—cashing a $40 check for pies baked for her Methodist church. Beneath this seemingly mundane errand lay the power to alter the destiny of her hometown bank. What seemed like an everyday banking transaction soon evolved into a pivotal lesson on community, dignity, and the enduring power of local values.
The Importance of Community Banks
Community banks have long served as the backbone of small towns and rural America. Unlike their larger, national counterparts, these banks focus primarily on local relationships and reinvest much of their capital back into their communities. Farmers & Merchants Bank, founded in 1968 by George, exemplifies this ideal. George’s philosophy was rooted in inclusiveness and empathy—he believed that farmers, widows, and working families, often overlooked by major financial institutions, deserved dignity and respect.
According to the Federal Deposit Insurance Corporation (FDIC), community banks provide approximately 60% of small business loans and over 80% of agricultural loans in the United States, making them instrumental for economic resilience and development in their regions.
A Collision of Appearances and Protocols
Upon entering the bank, the widow met Brandon Pierce, a relatively new and young branch manager. As she attempted to cash the check, Brandon scrutinized her outward appearance and requested identification with reluctance. His pointed comment—“We have to be careful with people like you”—echoed a bias rooted in first impressions rather than evidence. The public nature of the exchange drew stares from other patrons, challenging the long-held sense of trust she had placed in her local bank of fifty-eight years.
Research by psychologists, including Dr. Susan Fiske at Princeton University, reveals that snap judgments based on appearances are common but often inaccurate. Such judgments can undermine trust and alienate individuals, especially in close-knit rural communities.
Unveiling the Bank’s Founding Promise
Instead of escalating the situation, the widow calmly asked Brandon to reference account number 0001. This request was not arbitrary—it drew upon a crucial clause her late husband had embedded within the bank’s original merger agreement. Recognizing the account, Brandon’s confidence faded. The significance of account 0001 was soon apparent: it bestowed upon its holder the unique authority to prevent branch closures and prohibit staff reductions, serving as a protective covenant for the community’s interests.
This safeguard, highlighted by the bank’s response, shows how historical foresight can serve as a structural check against abrupt corporate decisions that may not align with local needs. Mergers and consolidations, now common in the banking sector, sometimes risk eroding these layers of localized protection unless counterbalances are explicitly included.
The Threat of Branch Closures in Rural Communities
The incident exposed Brandon’s secret plan to close the branch and reduce staff—a scenario not uncommon today. According to Reuters, over the past two decades, thousands of rural bank branches in the United States have shut down, citing cost efficiencies and digital banking trends. These closures often create “banking deserts,” limiting financial access and severely impacting rural populations, particularly seniors, the unbanked, and those without reliable internet.
The community covenant embedded in account 0001 represents one approach to preserving local banking services when broad industry forces work against small-town interests.
Reversal and Accountability: A Learning Opportunity
With the corporate head office interrupted and the community’s trust on the line, the decision to shut down the branch was swiftly overturned. Rather than seeking punitive action against Brandon, the widow recognized a broader opportunity for education and empathy. She requested not his dismissal, but for him to work at the teller window in ordinary clothes and to join her each Saturday in the garden—experiencing firsthand what it meant to be on the other side of judgment.
Such restorative approaches resonate with contemporary leadership and human resources best practices. Experts say fostering empathy and understanding, rather than retribution, leads to long-lasting organizational change. By inviting Brandon to share in tasks like gardening and to interact personally with local customers, the intent was to build compassion, humility, and appreciation for the diverse backgrounds making up the bank’s clientele.
The Evolution of a Banker: Restoring Community Traditions
Over the course of the summer, this transformation became palpable. Brandon went beyond administrative duties: he learned the names of customers, made visits to area farms, and brought back small traditions such as the iconic peppermint bowl at the counter. His actions rekindled long-standing rituals symbolic of trust and personal connection in community banking.
This renewal was not an isolated case. Studies, such as those by the American Bankers Association, suggest that when bank employees invest in customer relationships and the well-being of their communities, customer loyalty increases and the quality of service improves.
Transition to a Community Trust
Recognizing the evolving needs of Millbrook, the widow chose to transition account number 0001 into a community trust. This move democratized the power originally reserved for her family, enabling local residents to collectively guide decisions concerning their bank. Community trusts are increasingly popular vehicles for preserving local control over critical services, ensuring decisions made reflect collective values and needs.
Modern examples of community trusts worldwide have shown success in preserving local assets—from real estate to vital services—keeping them out of the hands of distant corporations or speculative investors.
The Enduring Value of Dignity in Everyday Banking
One of the final scenes speaks to the lasting impact of such changes. When a cleaning woman, wearing bleach-stained sneakers and holding one form of identification, came to cash her paycheck, Brandon responded with kindness and practical assistance. He not only cashed her check but offered to help her open an account—restoring a sense of welcoming and inclusivity that had defined the bank for decades.
Acts of everyday dignity—acknowledging the value of each individual, regardless of their outward appearance or material status—are consistent with research conducted by the best practices for customer service in banking. Such behaviors foster lasting trust and are proven to benefit both clients and financial institutions over time.
Societal and Industry Reactions: A Model for Modern Banking
Although fictionalized, stories like this resonate with both industry leaders and the general public, as they highlight systemic issues and potential remedies within the broader financial sector. International experts underscore the need for strong consumer protections, local control mechanisms, and service transparency in an era characterized by increasing automation and remote banking.
The preservation of local branches and the nurturing of community leadership are seen as crucial components of banking inclusion and economic resilience, especially for populations at risk of financial marginalization. Lessons drawn from this scenario provide a model for banks facing similar crossroads around the world.
Conclusion: The Legacy of Account Number 0001
This account is a testament to the pivotal role of community spirit, resilience, and the fundamental importance of treating people with dignity. When personal narratives intersect with foundational values, entire towns can be uplifted—ensuring banking remains accessible to all, and that respect is extended before a person’s worth is ever measured in dollars or appearances. It’s a timeless reminder that the legacy of leaders like George, and those who carry their vision forward, endures in the choices made every day, for every customer.
Sources
- FDIC – Community Banking Research
- Reuters – Rural Americans Lose Access to Local Bank Branches
- American Bankers Association – The Importance of Community Banking
- CNBC Select – Best Banks for Customer Service
- American Psychological Association – The Science of First Impressions
- The Guardian – Bank Branch Closures Hit Rural Communities Hardest
Disclaimer: This content is intended for entertainment purposes only and is not based on real events.